Direct to Consumer, State by State · 2026-2027 edition
Direct to Consumer, State by State
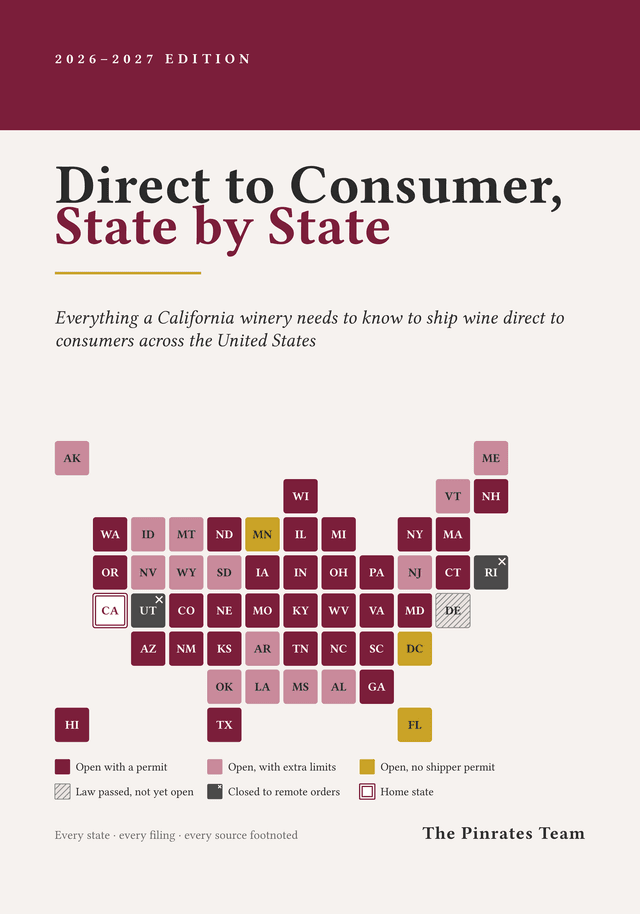
Direct to Consumer, State by State is the Pinrates guide for California wineries shipping direct to consumers in every other state. The book is current as of September 29, 2026. Each state's page below carries any change after that date, and every source the chapter cites.
What's inside
- Part One, Before You Ship: How direct shipping works, The federal layer, Opening a new state, Bought here, shipped home.
- Part Two, The States: a chapter for each of the 51 jurisdictions, each laid out the same way: the short version, getting licensed, what you can ship, taxes, returns and reports, labels, bonds, and a twelve-month calendar.
- Part Three, Reference: the master filing calendar, recent changes, the states side by side, the agency directory, a glossary, and how the book was researched.
The digital edition, free
The complete book as a PDF (477 pages, version 1.1), the same pages as print, in color, with every reference live: contents, page references, index, and the short links to each source. It is tagged for screen readers (PDF/UA-1). We email you a link to your own copy.
The print edition
A 7 by 10 inch paperback, $39.95, in preparation. This page will link to it when it is on sale.
The states
- AlabamaOpen, with extra limits
- AlaskaOpen, with extra limits
- ArizonaOpen with a permit
- ArkansasOpen, with extra limits
- CaliforniaHome state
- ColoradoOpen with a permit
- ConnecticutOpen with a permit
- DelawareLaw passed, not yet open
- District of ColumbiaOpen, no shipper permit
- FloridaOpen, no shipper permit
- GeorgiaOpen with a permit
- HawaiiOpen with a permit
- IdahoOpen, with extra limits
- IllinoisOpen with a permit
- IndianaOpen with a permit
- IowaOpen with a permit
- KansasOpen with a permit
- KentuckyOpen with a permit
- LouisianaOpen, with extra limits
- MaineOpen, with extra limits
- MarylandOpen with a permit
- MassachusettsOpen with a permit
- MichiganOpen with a permit
- MinnesotaOpen, no shipper permit
- MississippiOpen, with extra limits
- MissouriOpen with a permit
- MontanaOpen, with extra limits
- NebraskaOpen with a permit
- NevadaOpen, with extra limits
- New HampshireOpen with a permit
- New JerseyOpen, with extra limits
- New MexicoOpen with a permit
- New YorkOpen with a permit
- North CarolinaOpen with a permit
- North DakotaOpen with a permit
- OhioOpen with a permit
- OklahomaOpen, with extra limits
- OregonOpen with a permit
- PennsylvaniaOpen with a permit
- Rhode IslandClosed to remote orders
- South CarolinaOpen with a permit
- South DakotaOpen, with extra limits
- TennesseeOpen with a permit
- TexasOpen with a permit
- UtahClosed to remote orders
- VermontOpen, with extra limits
- VirginiaOpen with a permit
- WashingtonOpen with a permit
- West VirginiaOpen with a permit
- WisconsinOpen with a permit
- WyomingOpen, with extra limits
Corrections
Errata in the text, by the digital version that fixes them (this is version 1.1):
- Version 1.1. The "Your year in" calendars: long filing names and due dates now wrap inside their own columns instead of running into the months or off the page, and every calendar's key fits on the page. October 21, 2026.
Changes to federal rules after September 29, 2026:
None recorded.
Found something that has changed or is wrong? Write to support@pinrates.com.
Part One sources
The federal rules and other sources cited in Part One, chapter by chapter.
Part One · Chapter 1 · How direct shipping works
Statutes
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-01 | U.S. Const. amend. XXI, § 2 | ||
| us-04 | Webb-Kenyon Act | 27 U.S.C. § 122 | |
| us-05 | Twenty-first Amendment Enforcement Act | 27 U.S.C. § 122a | |
| us-06 | Basic permits conditioned on compliance with the Twenty-first Amendment | 27 U.S.C. § 204(d) | |
| us-09 | Intoxicating liquors nonmailable | 18 U.S.C. § 1716(f) |
Agency guidance and other sources
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-03 | State shipping laws | TTB, Business Central, "Requirements for Wineries" | TTB |
Part One · Chapter 2 · The federal layer
Forms
Statutes
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-12 | Basic permit to produce wine and ship it in interstate commerce | 27 U.S.C. § 203(b) | |
| us-06 | Basic permits conditioned on compliance with the Twenty-first Amendment | 27 U.S.C. § 204(d) | |
| us-18 | No bond for taxpayers eligible for quarterly or annual payment | 26 U.S.C. § 5551(d) | |
| us-22 | Wine tax rates by class | 26 U.S.C. § 5041(b) | |
| us-23 | Credits, hard cider, combined wineries, separate returns | TTB, "Craft Beverage Modernization Act" guidance and FAQs | |
| us-28 | Payment due the 14th day after the period | 26 U.S.C. § 5061(d) | |
| us-34 | Labeling required for interstate shipment | 27 U.S.C. § 205(e) | |
| us-09 | Intoxicating liquors nonmailable | 18 U.S.C. § 1716(f) | |
| us-04 | Webb-Kenyon Act | 27 U.S.C. § 122 |
Regulations
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-10 | Application to establish bonded wine premises, TTB F 5120.25 | 27 CFR 24.105 | |
| us-13 | Basic permit application, TTB F 5100.24 | 27 CFR 1.25 | |
| us-15 | Duration of basic permits | 27 CFR 1.43 | |
| us-17 | Wine bond | 27 CFR 24.146 | |
| us-19 | Excise return periods, due dates, eligibility, no-tax periods, September rule | 27 CFR 24.271 | |
| us-20 | Bond when liability exceeds $50,000 | 27 CFR 24.154 | |
| us-21 | Tax determined at removal from bonded premises | 27 CFR 24.270 | |
| us-26 | Conversion table | 27 CFR 24.300(a) | |
| us-27 | Pre-CBMA small-producer credit text | 27 CFR 24.278 | |
| us-31 | Failure to file | 27 CFR 24.274 | |
| us-35 | Certificate of label approval | 27 CFR 4.50 | |
| us-36 | 90-day decision on label applications | 27 CFR 13.21 | |
| us-37 | Government health warning | 27 CFR 16.21 | |
| us-38 | Record of taxpaid removals, including direct shipment | 27 CFR 24.310 | |
| us-39 | Standards of fill | T.D. TTB-200, 90 Fed. Reg. 1868 (Jan. 10, 2025) | |
| us-40 | Alcohol Facts and allergen labeling | TTB Notices 237 and 238, 90 Fed. Reg. 14932 (Apr. 7, 2025) | |
| us-41 | FDA food facility registration renewal, October 1 to December 31 of even-numbered years | 21 CFR 1.230 | |
| us-42 | Retail food establishment definition | 21 CFR 1.227 |
Agency guidance and other sources
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-11 | Winery premises required at 0.5% alcohol | TTB, Alcohol FAQs | TTB |
| us-14 | No federal fee | TTB, "Wine Permits" | TTB |
| us-03 | State shipping laws | TTB, Business Central, "Requirements for Wineries" | TTB |
| us-25 | Net rates after credits | TTB, "Tax and Fee Rates" | TTB |
| us-29 | TTB, "Due Dates for Tax Returns" (2026) | TTB | |
| us-30 | Signing authority | TTB, "Pay.gov" | TTB |
| us-32 | Executive Order 14247 | TTB, "Electronic Payment Mandate" | TTB |
Part One · Chapter 3 · Opening a new state
Statutes
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-09 | Intoxicating liquors nonmailable | 18 U.S.C. § 1716(f) |
Part One · Chapter 4 · Bought here, shipped home
Forms
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| ks-24 | Wine bought face to face at an out-of-state winery and transported or shipped home | Kansas Department of Revenue, Individual's Gallonage Tax Return, form ABC-207 (Rev. 01/23) | Kansas Department of Revenue |
Statutes
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| ri-01 | Shipping ban | R.I. Gen. Laws § 3-4-8 | |
| nc-28 | Wine bought while visiting a winery may be shipped by common carrier in amounts that can be personally transported | N.C. Gen. Stat. § 18B-109(d) | |
| us-55 | Direct shipment of wine bought in person at a winery | 27 U.S.C. § 124 | |
| us-56 | "What does Federal On-Site mean?" | Wine Institute, State Shipping Laws FAQs | |
| us-43 | Exempts property the contract requires to be shipped, and that is shipped, out of state by the retailer, including by delivery to a carrier or forwarding agent whether or not hired by the purchaser | Cal. Rev. & Tax. Code § 6396 | |
| us-04 | Webb-Kenyon Act | 27 U.S.C. § 122 | |
| us-53 | Alcoholic beverages nonmailable | 18 U.S.C. § 1716(f) | |
| ne-23 | Personal import limits | Neb. Rev. Stat. § 53-194.03 | |
| ut-06 | Liquor brought into Utah for personal use | Utah Code § 32B-4-414 | |
| us-59 | An individual may transport up to five gallons of wine into the state for personal or household use | Tenn. Code Ann. § 57-3-401(b)(2) | |
| us-51 | Retailer engaged in business in every district above $500,000 of combined sales in or for delivery in California | Cal. Rev. & Tax. Code § 7262, as amended by AB 147 (2019) |
Regulations
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| us-44 | Shipments outside the state | Cal. Code Regs. tit. 18, § 1620(a)(3)(B) |
Agency guidance and other sources
| Key | What it is | Form / cite | Agency |
|---|---|---|---|
| ga-24 | Winery with a federal basic permit may ship to a consumer who bought while physically present on the premises | O.C.G.A. § 3-6-32 | |
| ks-23 | Sale and shipment by a licensed wine manufacturer to a consumer who bought while physically present on its premises | K.S.A. 41-104(a)(7) | |
| us-57 | Federal on-site provision no longer applies to Delaware consumers from August 15, 2026 | Wine Institute, Delaware direct shipping page | |
| us-45 | Sale exempt where the contract provides for out-of-state shipment, the goods are so shipped, and the retailer delivers them to the carrier | CDTFA Annotation 325.0480 | |
| us-46 | The seller must obtain and retain documentary evidence of delivery to a carrier | CDTFA Annotation 325.0696 | |
| us-47 | Display material delivered to the purchaser in California is taxable even though later shipped out of state | CDTFA Annotation 325.0380 | |
| us-48 | Property delivered to a carrier or forwarding agent, even one hired by the purchaser, keeps its interstate status | CDTFA Annotation 325.1531 | |
| us-49 | Delivery to a carrier supplied by the purchaser, as the contract required, was an exempt interstate sale | CDTFA Annotation 325.0257 | |
| us-58 | Individuals cannot ship alcohol | FedEx, Shipping alcohol | |
| mn-02 | Minnesota House Research, Importation of Liquor for Personal Use (Nov. 2024) | ||
| us-50 | As of October 1, 2026 | Tennessee ABC, Fulfillment House Licenses | |
| us-60 | The licensee must control fulfillment and shipment | California ABC, Industry Advisory: Third Party Providers (Nov. 1, 2011) | |
| ca-04 | CDTFA, Local and District Tax Guide for Retailers | CDTFA | |
| us-52 | CDTFA, Use Tax Collection Requirements Based on Sales into California |